It’s Thursday afternoon. Payroll goes out tomorrow. You check the bank balance, then check it again, because the number doesn’t match the business you know you’re running.
The P&L says you had a good quarter. Sales are up. Your accountant told you last month that the margins look healthy. And yet here you are, moving money between accounts, deciding which supplier can wait another week, and wondering how a business that’s “doing well” can feel this tight.
If that sounds familiar, you’re in good company. Cash flow is the concern I hear most from business owners right now, more than profit and more than sales. Costs have gone up across the board: wages, insurance, rent, fuel, finance. Very few of them have come back down. Customers are taking longer to decide, and in plenty of industries, longer to pay.
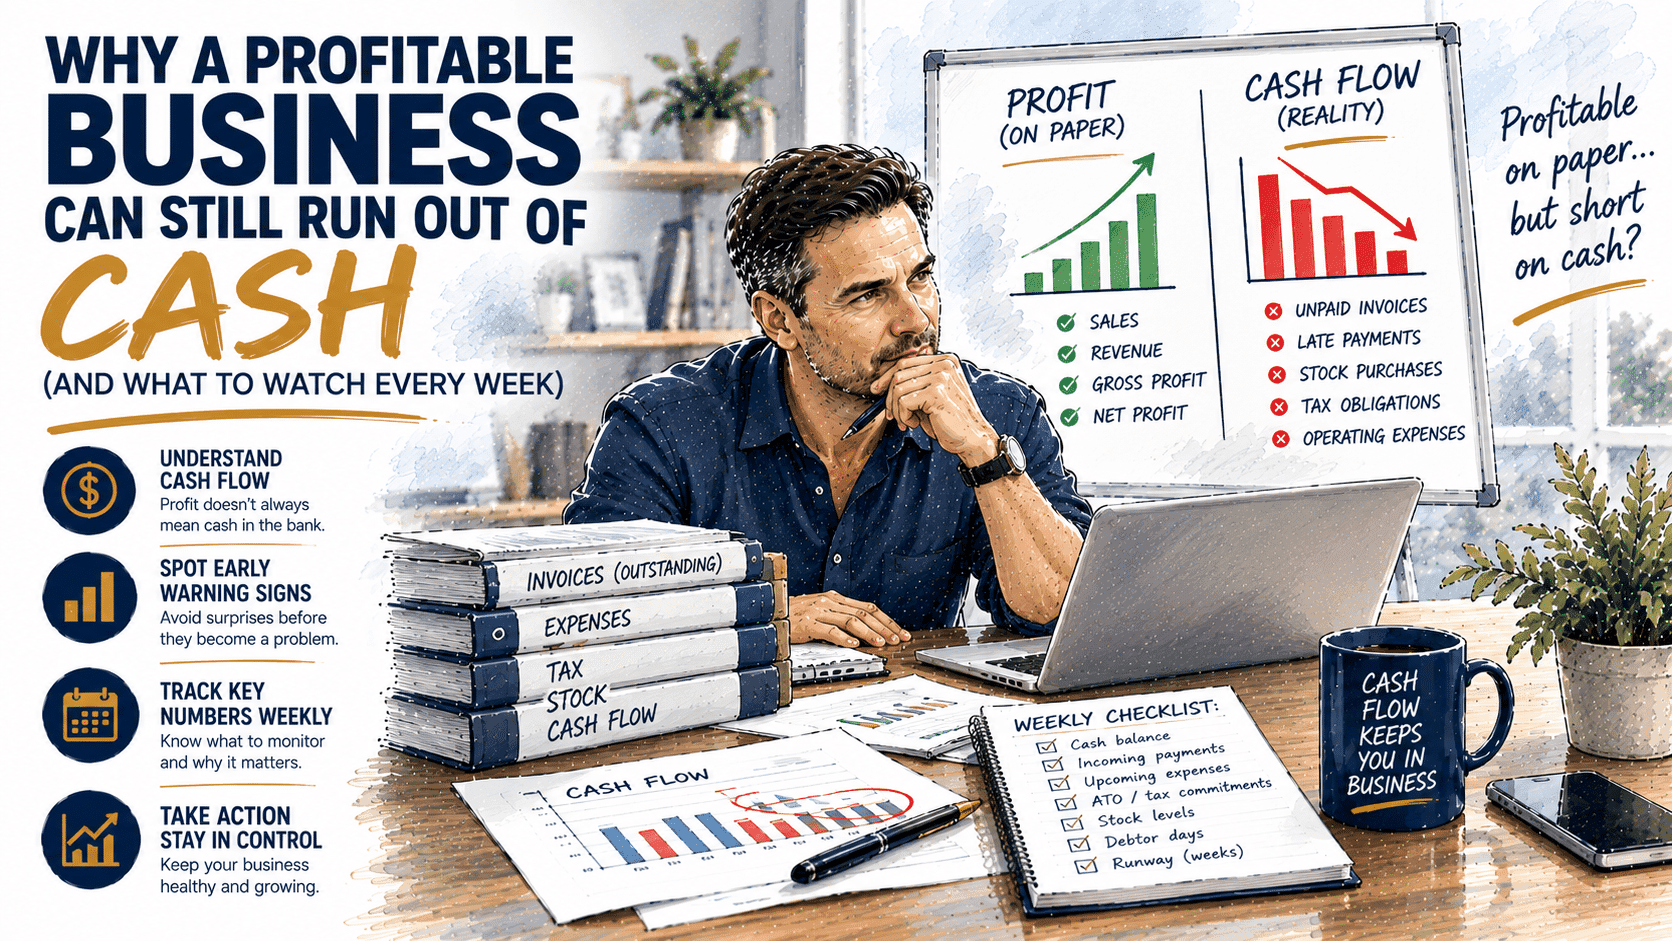
Here’s the thing: profit and cash are not the same, and they don’t move together. Profit is an opinion about how the business performed. Cash is a fact about what’s in the bank today. That gap, cash flow vs profit, is where most of the stress in a growing business actually lives.
Let’s unpack why profitable businesses get squeezed, which numbers to watch, and how to take back control. For a deeper look at the five levers that control cash flow in your business, see my financial management coaching page.
Cash Flow vs Profit: Why They Drift Apart
The gap between the two is where most cash stress lives. These are the five places I see it most often.
Customers are paying slower. You did the work in July, invoiced in August and got paid in October. On paper that’s July revenue. In the bank it’s October cash, and you funded the gap.
Growth eats cash first. More work means more wages, materials and stock up front, well before the money comes in. The faster you grow, the harder this bites. Plenty of good businesses have grown themselves into a cash crisis.
Stock and work in progress sit still. Materials on the shelf and half-finished jobs are cash you’ve already spent that isn’t earning anything yet.
Costs rose, prices didn’t. Insurance up, rent up, wages up. If your pricing hasn’t kept pace, your margin has quietly shrunk and every job now generates less cash than it used to.
The big bills arrive in lumps. BAS, super, insurance renewals, tax instalments. They’re completely predictable, but if you’re not setting money aside for them, every quarter feels like an ambush.
A Simple Framework: The Cash Conversion Chain
Every dollar in your business moves through the same four steps:
Win the work → Do the work → Invoice the work → Collect the cash
Profit gets booked in the middle of that chain. Cash only turns up at the end. Every day of delay between those steps is a day your business is acting as your customer’s bank.
The Three Numbers to Watch Every Week
You don’t need a finance degree to stay on top of cash. You need three numbers, checked on the same day every week.
1. Debtor Days
How long, on average, your customers take to pay you.
Formula: (trade debtors ÷ revenue for the period) × days in the period
If your terms are 14 days and this number is sitting at 45, you’ve got a problem hiding in plain sight.
2. Gross Margin
What’s left from each sales dollar after direct costs.
Formula: (revenue minus direct costs) ÷ revenue × 100
Watch the trend, not just the number. A slide of two or three points over a few months usually means your costs moved and your prices didn’t.
3. Cash on Hand in Weeks
How many weeks you could keep running if no money came in at all.
Formula: cash in the bank ÷ average weekly outgoings
Under four weeks, you’re making decisions under pressure. Eight or more, you’re making them from a position of strength.
Put all three on one page. Same day, same time, every week. The point isn’t the spreadsheet. The point is seeing the problem six weeks before it lands, not on the Thursday before payroll.
A Quick Self-Check
Answer these honestly. If you say yes to two or more, cash flow deserves an hour of your attention this week.
- Have you checked the bank balance more than once in a day to decide whether you can pay something?
- Do you know your debtor days right now, without looking it up? (If not, count that as a yes.)
- Has a BAS, super or insurance payment caught you short in the last 12 months?
- Have your costs gone up this year without a matching review of your prices?
- Are you growing, but feeling tighter than you did when the business was smaller?
None of these mean the business is in trouble. They mean the business is running on hope rather than visibility, and visibility is the easier one to fix.
How to Take Back Control of Your Cash
Let’s shift from “I hope it’s a good month” to “I know what’s coming and I’ve planned for it.”
1. Tighten Your Terms and Your Follow-Up
Most late payments aren’t malicious. They happen because nobody asked.
- Invoice the day the work is done, not at the end of the month
- Shorten your terms where you can, and put them clearly on every quote
- Set a follow-up rhythm: a reminder the day before it’s due, a phone call at seven days overdue
The squeaky wheel gets paid first. Make sure it’s you.
2. Ask for Money Up Front
Deposits and progress payments aren’t rude. They’re normal business.
- Take a deposit before you order materials or lock in the job
- Break larger jobs into staged payments tied to clear milestones
- Stop funding your customers’ projects with your own cash
If a customer won’t pay a deposit, that tells you something about how the final invoice is going to go.
3. Review Your Pricing, Not Just Your Costs
Cutting costs has a floor. Pricing has far more room to move.
- Check gross margin by job type or product line, not just the overall figure
- Find the work that’s quietly losing money, then reprice it or stop doing it
- Build known cost increases into your quotes before they land, not after
A small price rise on the right work often does more than months of cost cutting. If margin is the real issue rather than timing, see How to Increase Profit Margins in Your Small Business for the full pricing and delegation framework.
4. Put a Forward Forecast in Place
Your P&L looks backwards. A cash forecast looks forwards, and it’s the single biggest shift I see in business owners who go from reactive to in control. I’ve written a full step-by-step walkthrough of how to build one, including a spreadsheet layout you can copy, in Cash Flow Forecasting for Sydney Small Businesses.
5. Set Money Aside Before You Need It
Tax and super shouldn’t sit in the same account you run the business from. The business.gov.au cash flow guide has a good breakdown of how to plan around GST and PAYG obligations if you want the compliance detail alongside this.
- Open a separate account for GST, PAYG and super
- Transfer a set percentage every time a customer pays
- Build a buffer account toward your target number of weeks of cash
Money you can’t see is money you won’t accidentally spend.
A Client Example: The Growing Distributor
A client runs a wholesale distribution business turning over around $5 million. She’d grown 30% in a year. Profit was up. Cash had disappeared.
To keep up with demand she’d been placing bigger stock orders, while her two largest customers had quietly stretched their payment times without anyone noticing.
We worked on:
- A 13-week cash forecast, reviewed every Friday with her bookkeeper
- Reordering based on actual sell-through rather than gut feel, freeing up cash tied in slow stock
- A direct conversation with her two biggest customers about terms, backed by the numbers
Within one quarter she’d stopped leaning on the overdraft. More importantly, she stopped dreading the end of the month.
Common Mistakes That Make Cash Flow Worse
- Treating the bank balance as a forecast. Today’s balance tells you nothing about next month’s BAS.
- Chasing more sales to fix a cash problem. More sales on the same terms usually means more cash going out first.
- Discounting without doing the maths. A 5% discount on a job with a 20% margin gives away a quarter of your gross profit.
- Leaving it all to the accountant. Your accountant reports what happened. You’re the one who can change what happens next.
- Waiting until it hurts. The best time to fix cash flow is while there’s still some in the bank.
Final Thought: Profit Keeps Score, Cash Keeps You in the Game
A profitable business that runs out of cash still stops. The good news is that cash flow is rarely a mystery. It comes down to a handful of numbers, a few habits, and the discipline to look every week, especially when the week is busy.
If you’re profitable on paper but tight in the bank, you’re not doing it wrong. You just need a clearer view and a better rhythm.
Want a fresh set of eyes on where your cash is actually going? Book a free Clarity Call. No pressure, just straight-talking ideas you can use right away.